What is titanium, and why is it strategically important now?
Titanium is a metallic element with the symbol Ti and atomic number 22. Since its discovery in 1791, it has become valued for a rare combination of high strength-to-weight ratio, corrosion resistance, heat resistance and biocompatibility.
For decades, titanium was discussed mainly as an aerospace material or as a corrosion-resistant alloy for chemical processing. That definition is now too narrow. Three structural changes have raised its strategic importance.
1. Geopolitical disruption exposed supply-chain concentration
Russia’s invasion of Ukraine highlighted the aerospace industry’s historical dependence on a small number of qualified titanium suppliers. Aircraft manufacturers and their tier suppliers have since developed alternative sources and rebalanced procurement. Airbus confirmed in its 2025 financial statements that it had developed multiple sourcing solutions for Russian-origin titanium and rebalanced supply.
Titanium substitution is not quick. Aerospace material must meet demanding specifications and pass customer-specific approvals. Qualification can cover chemistry, melt history, mechanical properties, nondestructive testing, process control and full traceability.
2. Energy transition and infrastructure broaden demand
Titanium is used where low weight and long-term corrosion resistance can justify its higher initial cost. Relevant applications include offshore and marine equipment, heat exchangers, desalination systems, hydrogen-related equipment and selected power-generation components.
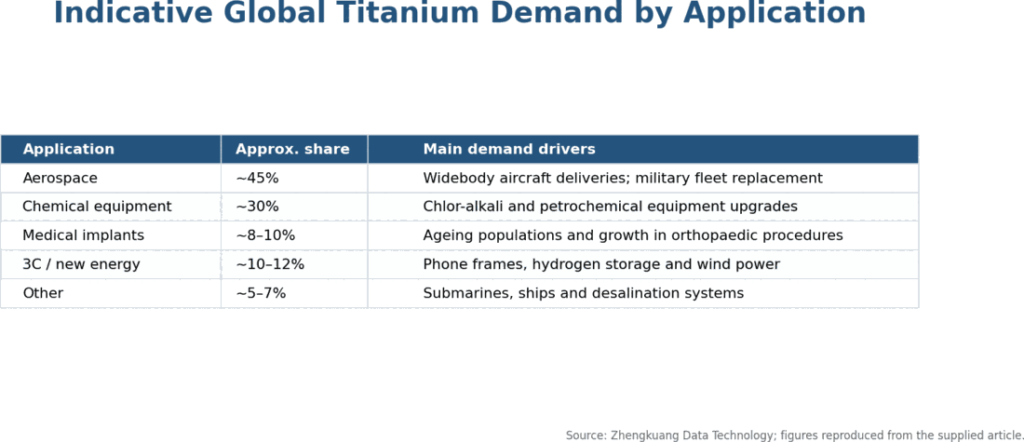
Demand drivers should nevertheless be described precisely. Titanium metal, titanium minerals and titanium dioxide pigment are related parts of the wider titanium value chain, but they are different markets with different products, economics and policy treatment.
3. Governments expanded critical-mineral policies
Titanium metal appears on both the strategic and critical raw-material lists under the EU Critical Raw Materials Act. The United States also assesses titanium supply chains through its critical-minerals framework. China’s materials policy emphasizes advanced nonferrous alloys, high-end applications, industrial upgrading and stronger domestic supply capability.
In short, titanium is moving from a specialist industrial material to a strategic resource governed by resilience, qualification and circularity.
China’s titanium industry: scale is established; quality is the next contest
China’s titanium industry has expanded across the value chain, from titanium-bearing feedstocks and sponge to ingot, mill products and finished components.
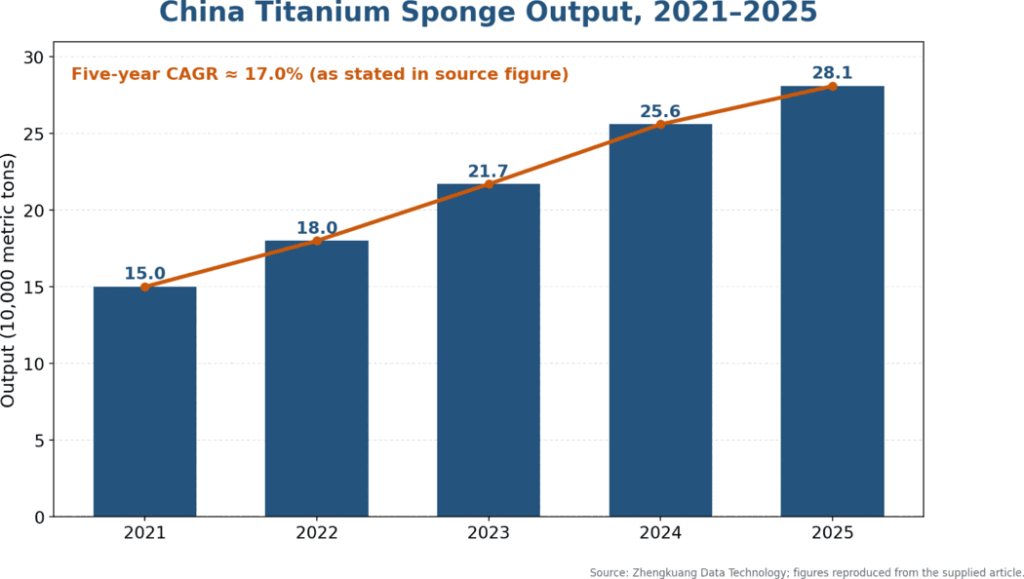
Industry data cited by the China Nonferrous Metals Industry Association’s Titanium, Zirconium and Hafnium branch indicate that Chinese titanium sponge output rose from approximately 150,000 metric tons in 2020 to about 281,000 metric tons in 2025. On that series, output increased by roughly 87% in five years, equivalent to a compound annual growth rate of about 13.4%.
Reported titanium mill-product output increased from approximately 97,000 metric tons in 2020 to 183,000 metric tons in 2025, also implying a compound annual growth rate of about 13.5%.
China titanium production snapshot
| Indicator | 2020 | 2025 | Approximate change |
| Titanium sponge output | 150,000 t | 281,000 t | +87% |
| Titanium mill-product output | 97,000 t | 183,000 t | +89% |
| Five-year CAGR, sponge | — | — | 13.4% |
| Five-year CAGR, mill products | — | — | 13.5% |
Note: Chinese industry-association statistics and USGS international datasets may differ because of reporting dates, revisions and definitions. Production, nameplate capacity and effective qualified capacity must not be treated as the same measure.
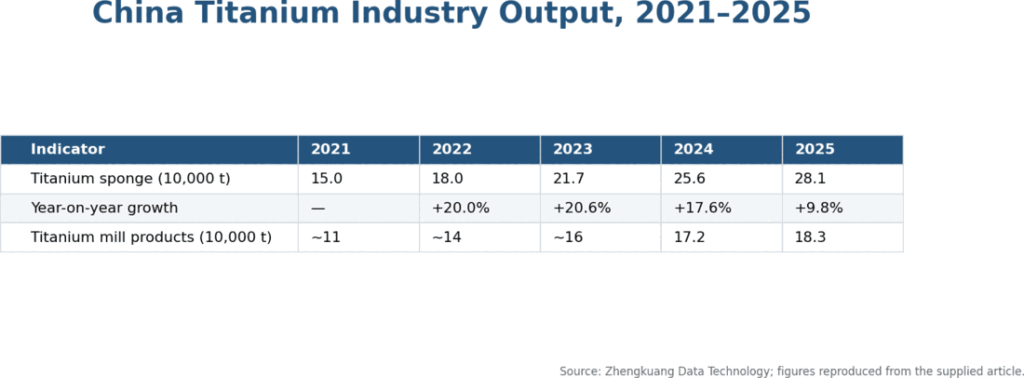
The strategic question is therefore changing. China no longer needs to prove that it can produce titanium at scale. It needs to increase the share of products that consistently meet the most demanding requirements in aerospace, medical, energy and other regulated markets.
Priority capabilities include:
- tight interstitial-element control, including oxygen limits appropriate to the specified grade;
- chemistry and microstructure consistency between heats and batches;
- vacuum melting and remelting control;
- reliable ultrasonic and other nondestructive testing;
- documented traceability from raw material to final product;
- internationally recognized quality systems and customer-specific process approvals.
This is why “more capacity” and “more qualified supply” are not equivalent.
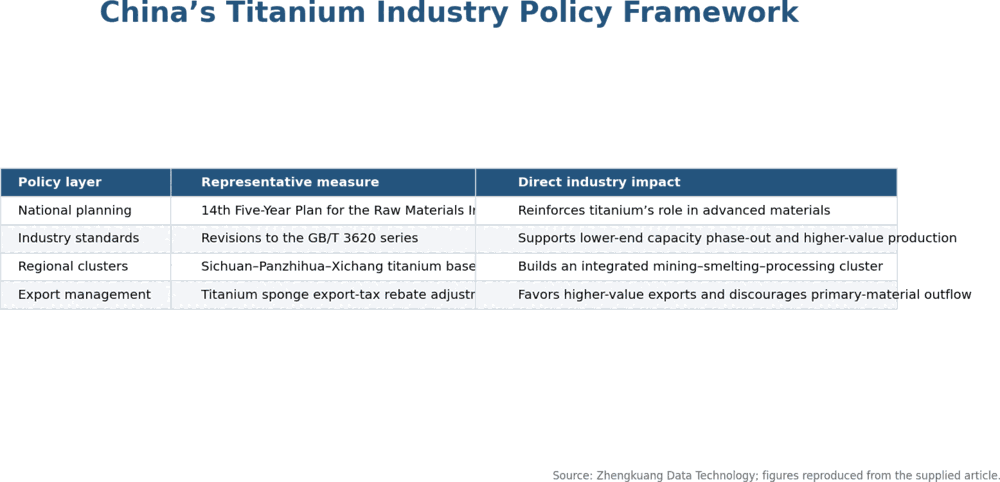
A concentrated global titanium sponge market
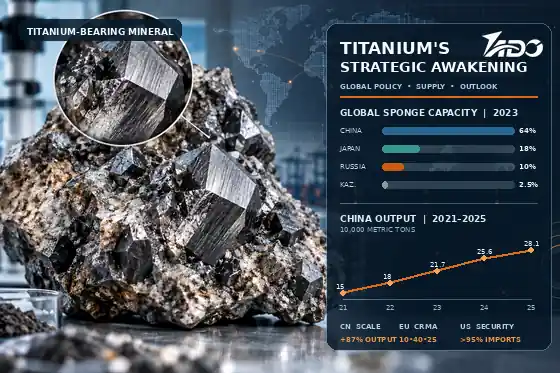
Titanium sponge production is concentrated in a small group of countries, principally China, Japan, Russia and Kazakhstan, with additional supply from countries including Saudi Arabia. Exact shares vary by year and by whether a dataset measures actual production or installed capacity.
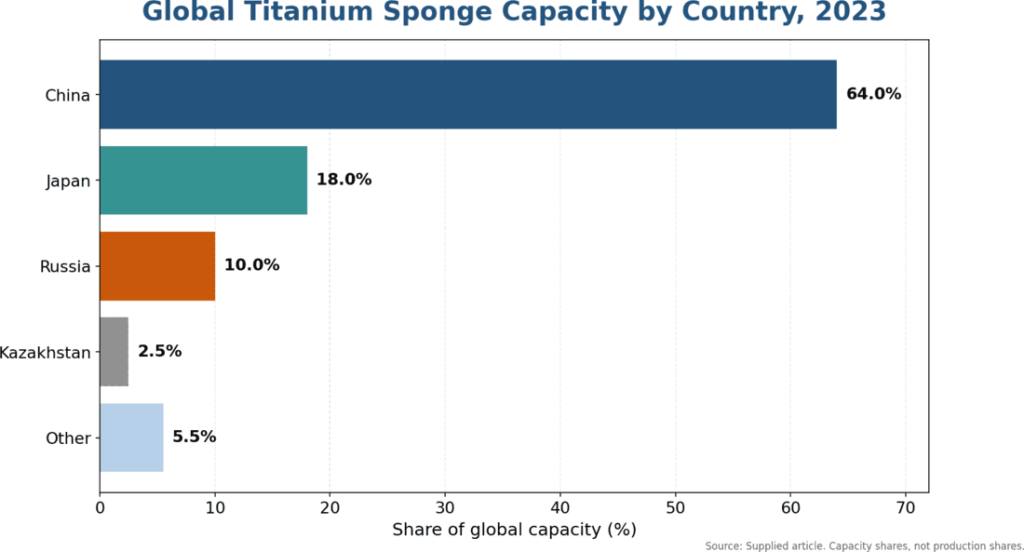
The market also has a second layer of concentration: not every ton of sponge is interchangeable. Aerospace and other safety-critical users require approved grades, repeatable quality, qualified melting routes and auditable documentation. As a result, a country may hold a large share of total output without holding the same share of immediately available aerospace-qualified supply.
How the major supply regions differ
| Economy | Main strategic position | Principal strength | Main constraint |
| China | Largest production base and broad value chain | Scale, industrial clusters and downstream manufacturing | Expanding the share of internationally qualified high-end supply |
| Japan | Major supplier to US and global aerospace chains | High-purity, consistent aerospace-grade sponge | Energy cost and concentrated production base |
| Russia | Historically important integrated aerospace supplier | Integrated sponge-to-mill-product capability | Sanctions risk, customer diversification and geopolitical exposure |
| Kazakhstan | Established non-Russian supply source | Integrated resource and sponge production | Smaller scale than China, Japan or Russia |
| United States | Major consumer with strategic aerospace demand | Advanced downstream melting, forging and aerospace manufacturing | No active domestic sponge production and very high import reliance |
European Union policy: the CRMA turns diversification into law
Regulation (EU) 2024/1252—the Critical Raw Materials Act, or CRMA—was adopted on 11 April 2024 and entered into force in May 2024. It lists titanium metal as both a strategic raw material and a critical raw material.
The distinction matters. The regulation is aimed at raw-material security for the green and digital transitions as well as defence and aerospace. It does not mean every titanium-containing consumer product receives strategic status.
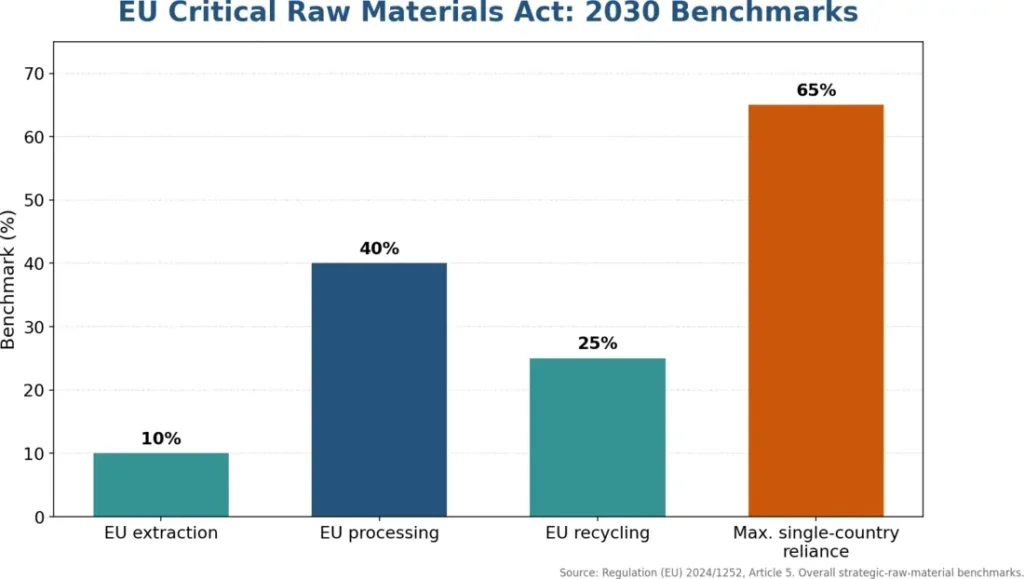
EU 2030 raw-material benchmarks
| Area | 2030 benchmark |
| EU extraction capacity | At least 10% of annual EU consumption, where feasible |
| EU processing capacity | At least 40% of annual EU consumption |
| EU recycling capacity | At least 25% of annual EU consumption |
| Dependence on one third country | No more than 65% at a relevant processing stage |
These are overall benchmarks for strategic raw materials under the CRMA; they should not be misread as four titanium-specific quotas guaranteed for every individual stage.
For titanium suppliers, the commercial implications are clear: European buyers will place greater weight on origin transparency, supply diversification, recycled content, environmental data and continuity planning.
United States policy: titanium through a national-security lens
The United States has treated titanium as a critical supply-chain issue since the first federal critical-minerals list was issued in 2018. The concern is especially acute for titanium sponge, the porous intermediate metal used to produce titanium ingot.
USGS reporting indicates that US titanium sponge production remains inactive and that net import reliance is above 95%. Japan is a particularly important source. The United States retains sophisticated downstream capabilities in melting, forging, rolling and aerospace component production, but the upstream sponge gap remains a strategic vulnerability.
This distinction is essential: the United States is not without a titanium industry, but it lacks active domestic production at a critical upstream stage.
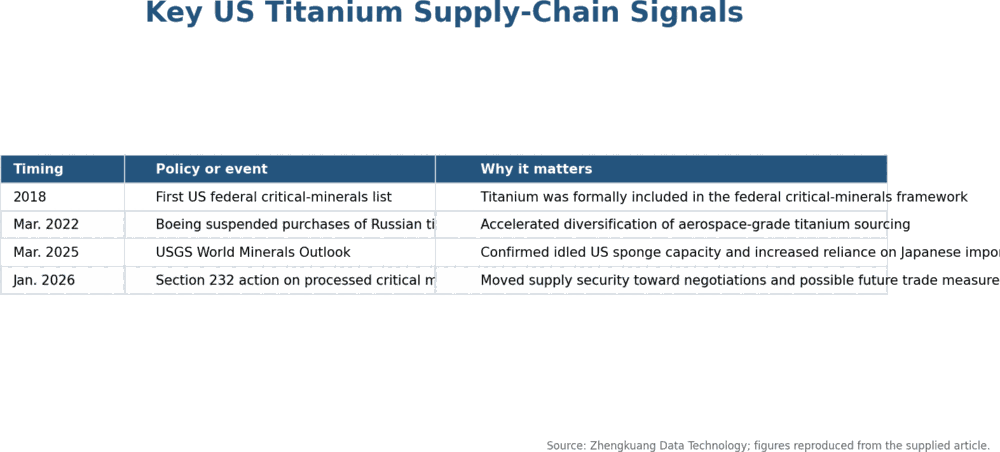
Defence and aerospace requirements reinforce the policy focus. Titanium is used in airframes, engines, naval equipment and other high-performance systems where strength, weight, temperature performance and corrosion resistance are mission-critical.
Russia and the aerospace titanium supply-chain stress test
Before 2022, VSMPO-AVISMA was deeply embedded in global aerospace supply chains. The war in Ukraine forced aircraft manufacturers to test how quickly a highly qualified, concentrated material base could be diversified.
Boeing suspended titanium purchasing from Russia in 2022. Airbus took a more gradual path and continued to identify Russian titanium as a supply-chain risk while developing multiple sourcing solutions. By its 2025 reporting, Airbus stated that it had rebalanced its titanium supply, but it did not disclose a sufficiently precise public percentage to support a definitive “Russian share” claim.
The broader lesson is more durable than any single percentage: alternative metal may exist, yet qualified alternative supply can still be scarce. New entrants must pass standards and approvals that may include AS9100, customer audits, special-process accreditation such as Nadcap, and material- or part-specific qualification.
China, the EU and the United States: policy comparison
| Dimension | China | European Union | United States |
| Core objective | Industrial upgrading and supply-chain capability | Resilience, diversification and circularity | Defence readiness and reduced import vulnerability |
| Policy approach | Planning, industrial clusters, standards and capacity development | Binding regulation, strategic projects and 2030 benchmarks | Critical-minerals policy, defence procurement and supply-chain investment |
| Titanium position | World’s largest sponge and mill-product base | Titanium metal is both strategic and critical under the CRMA | Critical upstream material with very high sponge import reliance |
| Main challenge | Raising qualified high-end output and avoiding low-end overcapacity | Scaling competitive domestic processing and recycling | Re-establishing or securing upstream sponge supply |
| Supplier opportunity | High-grade products, process control and global certification | Traceable, lower-carbon, diversified and recycled supply | Qualified non-Russian supply and secure long-term contracts |
Outlook to 2030: three high-confidence trends
1. Competition will move from volume to qualified quality
China is likely to remain the largest producer, but capacity alone will become less decisive. The higher-value contest will center on purity, consistency, melt route, traceability, testing, certification and performance in demanding end uses.
For buyers, the relevant question is no longer simply, “Can this supplier make titanium?” It is, “Can this supplier repeatedly deliver the specified grade, process route and documentation under controlled production conditions?”
2. De-risking will reshape trade flows, not eliminate globalization
European and US buyers will continue to diversify sourcing. Japan and Kazakhstan are positioned to remain important alternatives in aerospace-grade supply, while other producers may gain opportunities where they can meet qualification and cost requirements.
Reshoring will face practical limits: titanium sponge production is capital-intensive, energy-intensive and technically demanding. New capacity also requires stable demand and downstream qualification. The likely result is a more diversified international network rather than complete national self-sufficiency.
3. Titanium recycling will become commercially strategic
The CRMA’s 25% recycling benchmark strengthens the policy case for titanium scrap recovery. Closed-loop recycling can reduce primary-material demand and lower energy use, particularly when clean, well-segregated production scrap is returned to qualified melting routes.
However, “titanium is recyclable” does not mean all scrap can automatically return to the same high-value application. Alloy separation, contamination control, oxygen pickup, certification and traceability determine whether scrap is recycled into aerospace-grade metal, lower-grade products or other uses.
What this means for international titanium buyers
Buyers evaluating a titanium supplier should examine more than country of origin or quoted capacity. A robust sourcing review should include:
- Material definition: commercially pure titanium or alloy, grade, applicable ASTM/AMS/EN standard and dimensional specification.
- Production route: sponge source, melting and remelting route, forming process and heat-treatment history.
- Quality evidence: mill test certificates, chemistry, mechanical properties, microstructure and required nondestructive testing.
- Traceability: heat, lot and process records linked to the delivered material or component.
- Qualification scope: ISO 9001, AS9100 where relevant, Nadcap for applicable special processes, and customer-specific approvals.
- Supply resilience: alternative feedstock sources, energy exposure, lead times, inventory policy and business-continuity planning.
- Sustainability data: scrap management, recycled input, energy data and product-level environmental information where available.
Frequently asked questions
Is titanium a critical raw material?
Yes, but the exact designation depends on jurisdiction and product form. The EU CRMA lists titanium metal as both strategic and critical. The United States includes titanium within its critical-minerals and supply-chain security framework.
Which country produces the most titanium sponge?
China is the largest producer. Japan, Russia and Kazakhstan are also major suppliers. Market shares change by year and should be identified as either production shares or capacity shares.
Why is titanium sponge strategically important?
Titanium sponge is the primary metallic intermediate used to make titanium ingot. If sponge supply is interrupted, downstream melting and mill-product capacity cannot fully compensate without qualified alternative feedstock.
Can Chinese titanium enter European and US aerospace supply chains?
Technically, yes, but entry depends on far more than nationality or nominal grade. A supplier must meet applicable material specifications, quality-system requirements, process approvals, traceability rules and customer-specific qualification. This can take substantial time.
Why is titanium recycling becoming more important?
Recycling can reduce exposure to primary supply, cut energy demand and support CRMA circularity goals. The highest-value closed loops require clean scrap segregation, alloy control and qualification.
Conclusion
Titanium’s story is moving from the materials laboratory to boardrooms, procurement strategies and trade policy.
China has already established a decisive advantage in production scale. Its next challenge is to convert that scale into a larger share of consistently qualified, high-value products. Europe is using regulation to build resilience and circularity. The United States is focusing on the upstream gap created by its inactive sponge capacity. Aerospace manufacturers, meanwhile, are learning that replacing a strategic material supplier is a qualification problem as much as a capacity problem.
The next phase of the global titanium industry will therefore be defined by four words: quality, traceability, diversification and recycling.
The data are provided for industry research and general information only. They do not constitute investment advice.
Contact Us
for product specifications, samples, material declarations, testing documentation or wholesale cooperation.
Xi ‘an Taidou Metal Products Technology Co., Ltd.
Room 1604, Block D, Baihualin Financial Innovation Center, No. 51 Fengcheng Second Road, Weiyang District, Xi’an City, Shaanxi Province, P.R.China
Email: overjunjun@gmail.com
WhatsApp: +64274075362
Tel: +86 18629501987
- description: Explore global titanium policy, China’s production growth, EU and US supply risks, aerospace sourcing shifts and the outlook through 2030.
- dateModified: 2026-09-08
- author: TADO Editorial Team
- publisher: TADO
- mainEntityOfPage: https://tieedo.com/news/global-titanium-industry-policy-supply-trends/
- about: Titanium; titanium sponge; critical raw materials; aerospace supply chain
- citation: Add the primary-reference URLs listed above